
Selling a Business in Malaysia: What Should an Owner Do Before Looking for a Buyer?
•

Written by
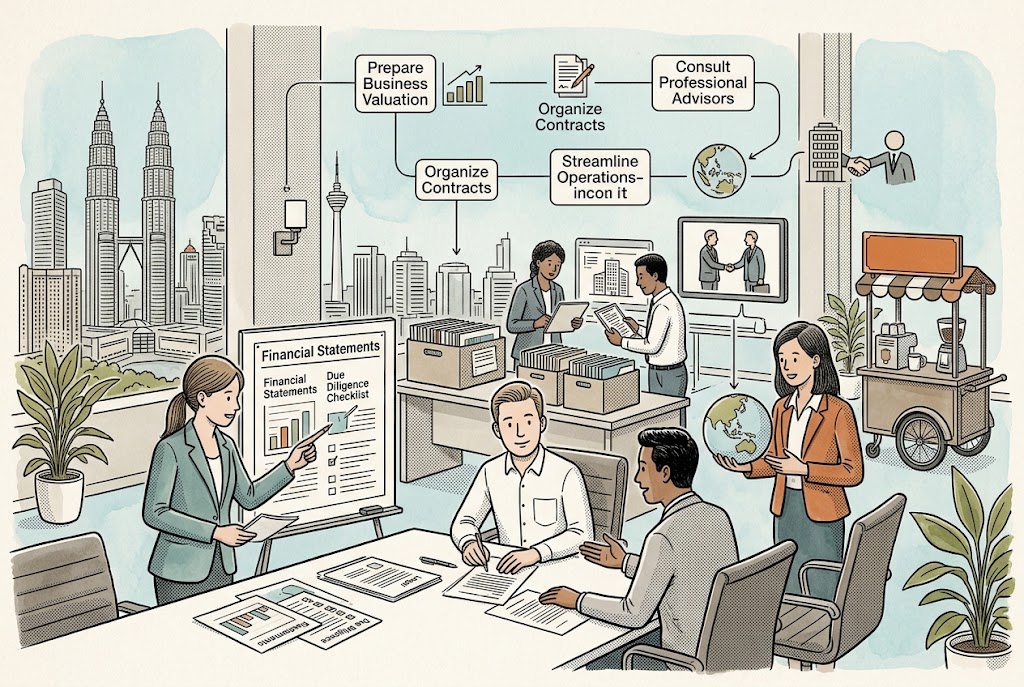
The best time to fix a problem in a business sale is usually before a buyer knows the business is for sale.
Owners often assume the first step is to find a buyer or agree a headline valuation. In practice, seller leverage is often shaped earlier: by whether ownership records are clear, shareholder rights are understood, major contracts can survive a change of control, key information is organised, and the business can operate without one founder holding everything together.
Preparing to sell a business in Malaysia is therefore not about making the company look flawless. It is about knowing what you are selling, what could obstruct the transaction, and what should be fixed while the seller still controls the timetable.
Decide what "selling the business" actually means for you
A full exit is only one possible outcome. You may want to sell a controlling stake but keep a minority interest, bring in a strategic investor, sell one subsidiary, divest part of a group, or reduce your ownership while staying involved in management.
Those outcomes create different preparation priorities. A founder seeking a clean exit will focus on certainty of payment, release from continuing obligations and post-completion exposure. A seller retaining a minority stake will also need to think about future governance, information rights, reserved matters, dividends and a later exit.
Before speaking to buyers, write down the commercial result you actually want: how much ownership you intend to sell, whether you will stay involved, whether deferred consideration is acceptable, and what level of control you are willing to give up.
Confirm who owns what before discussing a deal
Do not rely only on an informal cap table or founder memory. Check the registered shareholders and corporate records against any arrangements that may affect ownership, including options, convertible instruments, nominee arrangements, employee equity promises or old transfers that were never properly reflected in the records.
The purpose is to identify any mismatch between what the owners believe they can sell and what the documents actually show.
If several shareholders are involved, confirm whether they are aligned on the intended exit. A transaction becomes much harder when a seller discovers after buyer discussions start that another shareholder disputes the valuation, refuses to sell or has rights that change the proposed deal.
Read the constitution and shareholders' agreement for transfer restrictions
Ownership does not always mean shares can be transferred on any timetable to any buyer.
The constitution, shareholders' agreement and investment documents may contain pre-emption rights, consent requirements, rights of first offer or first refusal, tag-along rights, drag-along provisions, reserved matters or restrictions on transfers to particular persons.
These provisions can affect whether the proposed transaction is possible and how it should be sequenced. Review them before promising a buyer exclusivity, a completion date or an ownership outcome that may depend on other shareholders.
Work out whether the likely transaction is a share sale, asset sale or partial divestment
"Selling the business" can describe different legal structures. A buyer may acquire shares in the company, selected assets and operations, or only part of the owner's interest.
The distinction affects what transfers, what stays behind, what third-party consents may be required, how contracts and employees are dealt with, and where liabilities sit after completion.
You do not need to settle every structural point before approaching the market, but you should know whether there is an obvious reason one structure may be inconsistent with your exit objective.
For a fuller comparison, see our guide to asset purchase versus share purchase in Malaysia.
Get the company records into sale-ready condition
A buyer will eventually ask for evidence. Sellers lose time and credibility when basic documents cannot be located quickly.
Organise the records most likely to matter: corporate and ownership documents, licences and approvals, material customer and supplier contracts, financing documents, intellectual property records, employment documentation, pending or threatened disputes, insurance material and key tax or compliance records.
This is not the same as carrying out full vendor due diligence. The immediate goal is to identify obvious gaps and make sure the seller can support the business story being presented to buyers.
For the wider diligence process, see our guide to due diligence in mergers, acquisitions and business transactions.
Identify contracts and relationships that could become deal blockers
A strong business can still have contracts that make a sale difficult.
Review major customer, supplier, landlord, lender, licence, joint-venture and technology agreements for provisions that may be triggered by a sale or change of control. Look for consent requirements, termination rights, exclusivity provisions, non-assignment clauses, financing covenants and restrictions linked to ownership.
Also identify personal guarantees and security given by founders or related companies. A seller expecting a clean exit should know which obligations must be released, refinanced or otherwise dealt with at completion.
The commercial question is simple: who outside the seller-buyer relationship has leverage over whether the transaction can close?
Reduce over-dependence on the founder or one key person
Many owner-managed businesses are more dependent on the founder than the financial statements reveal.
The founder may hold the key customer relationships, approve pricing, control banking access, hold important passwords, manage supplier relationships and make the decisions that keep the business running.
A buyer will notice that concentration risk. It can affect confidence in the business after the seller leaves and may lead to requests for a long transition period, continued employment, consultancy obligations, deferred consideration or an earn-out.
Before sale discussions begin, identify which relationships and functions should be institutionalised or shared with the wider management team.
Protect confidentiality before approaching buyers
Putting a business on the market creates a tension: buyers need enough information to assess the opportunity, but premature disclosure can disrupt staff, customers, suppliers and competitors.
Plan the disclosure process before sending sensitive material. Decide who inside the company will know, when a non-disclosure agreement should be signed, what information can be included in an initial teaser, and what should only be released later in a controlled data room.
Highly sensitive information such as customer pricing, margins, trade secrets, employee remuneration or strategic plans does not always need to be disclosed at the first expression of interest.
Think about price as more than the headline number
A buyer offering RM20 million is not necessarily offering the same economic deal as another buyer offering RM20 million.
The seller needs to understand how the price will actually be paid and adjusted. Is the full amount payable at completion? Is part deferred? Is payment tied to future performance? Will there be a retention or escrow? Will completion accounts adjust the price for cash, debt or working capital?
At the preparation stage, you do not need to negotiate final drafting. But you should decide which forms of price structure are acceptable and which would undermine your intended exit.
Choose advisers before the deal becomes difficult to change
Legal, tax, accounting and corporate-finance advice is usually more valuable before the seller commits to a structure than after a buyer has already obtained exclusivity on agreed headline terms.
Corporate or M&A counsel can help identify ownership restrictions, consent requirements, transaction risks and the legal consequences of terms proposed in heads of agreement. Accountants and tax advisers can help the seller understand financial presentation and issues likely to be tested in diligence. A corporate-finance or M&A adviser may assist with valuation, buyer selection and running a competitive process.
The exact team depends on the size and complexity of the sale. The important point is timing: advisers are most useful while the seller still has choices.
Build a pre-sale action list before buyer outreach
Define the percentage of the business you are willing to sell.
Confirm who legally owns the shares or assets involved.
Check the constitution, shareholders' agreement and investment documents for transfer restrictions.
Identify whether a share sale, asset sale or partial divestment better fits the intended exit.
Organise the corporate, contractual, employment, IP and compliance records likely to be requested.
Map third parties whose consent or cooperation may matter.
Reduce dependence on one founder or key person where practicable.
Set a confidentiality and staged-disclosure process.
Decide which forms of deferred payment, earn-out, retention or adjustment are acceptable.
Bring in the right advisers before signing binding commercial commitments.
If several of those answers are unclear, the business is not necessarily unsaleable. It means the seller still has useful work to do while those problems remain under its control.
When does preparation become a live sale transaction?
Preparation ends when the seller starts engaging seriously with a buyer and the process moves into confidentiality arrangements, indicative offers, heads of terms, exclusivity, due diligence and negotiation of the sale agreement.
That is when broad commercial objectives become negotiated legal obligations. The seller's position on price, liability, timing, conditions, warranties, disclosures and post-completion involvement needs to be translated into the transaction documents.
Our business acquisition step-by-step guide explains the wider transaction sequence. If the exit is structured as a share sale, Legal That Works' Share Sale and Purchase Agreement service is the commercial destination for seller-side transaction structuring, drafting and negotiation.
Prepare before the buyer sets the agenda
Good pre-sale preparation does not mean trying to make the company look flawless. It means knowing where the weaknesses are, deciding which can be fixed, and entering the market with a clear view of what you are selling and what you are not prepared to concede.
If you are considering a full or partial share sale, speak with Legal That Works about preparing and negotiating the Share Sale and Purchase Agreement before binding terms narrow your options.
Frequently asked questions
How long should I prepare before selling a business in Malaysia?
There is no single preparation period. A business with clean ownership records, organised contracts and a management team that can operate without the founder may be ready quickly. A business with shareholder disputes, missing records or major consent issues may benefit from resolving those matters before buyer outreach.
Should I find a buyer before speaking to a lawyer?
You can explore buyer interest first, but legal input becomes especially valuable before you sign exclusivity, heads of terms or other commitments that narrow your options.
Can I sell only part of my company?
Potentially, yes. A seller may dispose of a minority or majority stake rather than all shares. The commercial and governance consequences differ because the seller may remain a shareholder after completion.
What documents should I organise before due diligence?
Start with records supporting ownership, operations and risk: corporate records, material contracts, financing documents, licences, intellectual property, employment documentation, litigation information and key compliance material.
Do employees or customers need to know before the sale?
Not necessarily at the earliest stage. The timing depends on the transaction, contractual obligations, regulatory requirements and disruption risk. Sellers should plan communications rather than allow information about the process to leak informally.
What if my shareholders' agreement restricts a sale?
The restriction must be read in its precise wording. It may require consent, an offer to existing shareholders, participation rights for other holders or a particular transfer process. Identify that requirement before promising a buyer a timetable or ownership outcome.
This article is for general information only and does not constitute legal advice. The appropriate structure and preparation steps depend on the company's documents, ownership, industry, transaction objectives and specific circumstances.
Disclaimer
The content provided on this website is intended for general informational and educational purposes only. It does not constitute legal advice, nor should it be relied upon as a substitute for professional consultation with a qualified lawyer. Every legal matter is unique, and you are strongly encouraged to seek tailored legal advice from a licensed legal practitioner before taking any action based on the information available here.
While we endeavour to ensure the accuracy and timeliness of the content, ASCOLAW and its affiliates make no representations or warranties of any kind, express or implied, about the completeness, accuracy, reliability, suitability or availability of the information contained on this website. Any reliance you place on such information is strictly at your own risk.
Author
AKMAL SAUFI MOHAMED KHALED
Managing Partner & Founder
Practice Area
Corporate
Commercial
Business Function
Related Post
Buying 100%, a Majority Stake or a Minority Stake: What Changes in the SPA and When Do You Also Need a Shareholders Agreement?
Buying Shares in a Malaysian Company: What Should the Buyer Negotiate in the Share Purchase Agreement?
Due Diligence Found a Problem: Should the Buyer Reduce the Price, Demand an Indemnity, Use Escrow or Walk Away?
What Does a Lawyer Review and Negotiate for a Buyer Before Signing a Share Purchase Agreement?
Conditions Precedent in a Share Sale: What Sellers Should Avoid Before Signing
Disclosure Letter in a Share Sale: How Malaysian Sellers Reduce Warranty Exposure
Earn-Outs and Deferred Purchase Price: What Sellers Need to Protect
How Does Selling a Company in Malaysia Work? A Seller's Roadmap From Buyer Approach to Completion
Seller Liability After a Business Sale: Caps, Time Limits and Warranty Claims
Selling a Business in Malaysia: What Should an Owner Do Before Looking for a Buyer?
